 Korean Stock Insight
KOSPI Rebounds 3.09% as Chip Supply Chain and Batteries Join the Rally
Korean equities recovered on October 27 with participation extending beyond the largest chipmakers. The KOSPI rose 3.09% to 5,638.34 and the KOSDAQ gained 2.29% to 743.83. Our reading is constructive on the breadth of the rebound, but the next test is whether earnings commentary can support the demand expectations that brought buyers back.
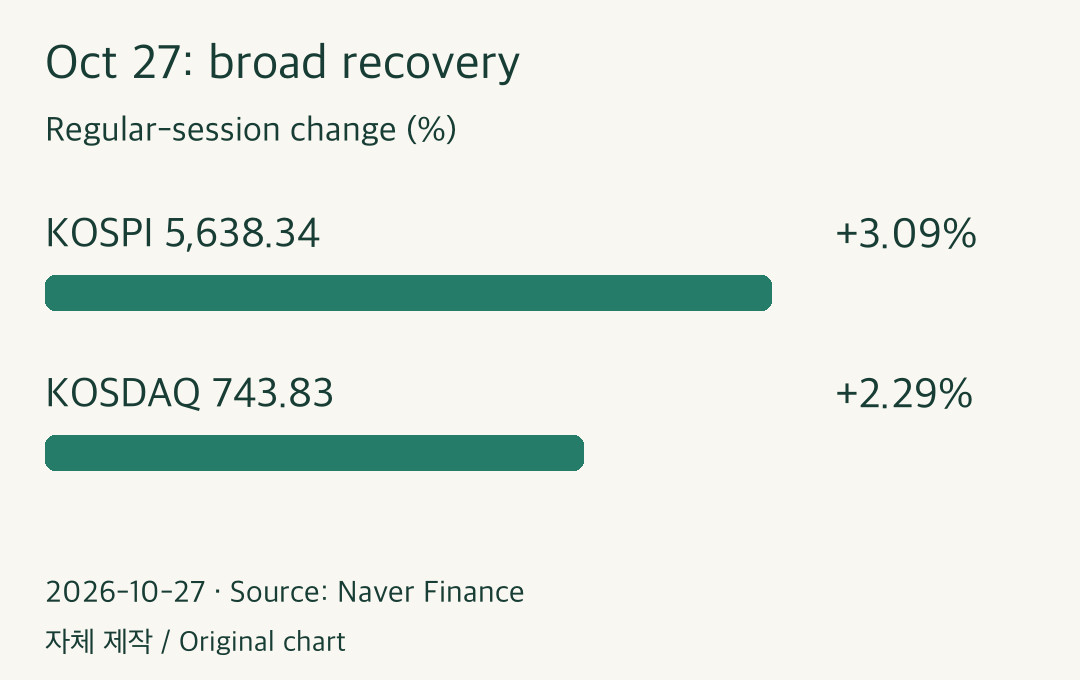
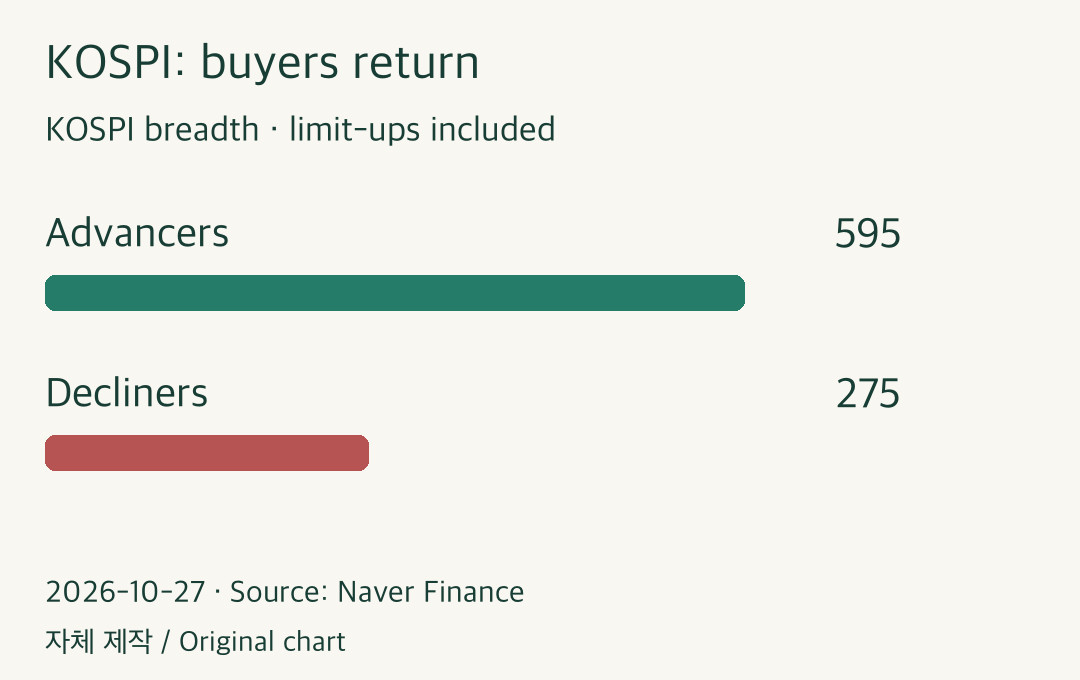
The intraday path was less convincing than the headline gain. The KOSPI opened at 5,658.65 and reached 5,737.61 before closing 99.27 points below that high. Still, Naver Finance counted 595 advancing KOSPI stocks against 275 decliners. On the KOSDAQ, the totals were 1,094 and 545, including limit-up and limit-down names. This was a broader recovery than an index move supported by only a few heavyweights.
Foreign investors and institutions bought on balance in both markets, while individuals were net sellers. Continued participation from those buyers would strengthen the recovery. The currency did not deliver the same signal: USD/KRW finished the 3:30 p.m. session at 1,323.7, up 0.6 won. Equity inflows alone should not be read as confirmation of a stronger won.
Memory led the move. Samsung Electronics closed at KRW 222,000, up 4.23%, and SK hynix at KRW 1,341,000, up 5.18%. Newsis and Seoul Economic Daily linked the improved mood to Anthropic’s reported US listing plans and renewed confidence in AI monetization. For Korean suppliers, the useful economic link is the ability of AI customers to fund continued computing investment. The more durable evidence would be actual purchasing and cash generation.
We would judge the upcoming memory results by demand, product mix and the cash available after investment. A customer spending increase need not translate proportionately into a supplier’s profit if pricing or mix deteriorates. SK hynix is due to report on October 28 and Samsung on October 29. Any additional shareholder return should be assessed against its announced terms, rather than treated as a committed payment in advance.
The supply-chain response was also notable: Samsung Electro-Mechanics gained 7.42%, Simmtech 9.23% and Wonik IPS 4.92%. These moves broaden the investment theme from finished memory to substrates and manufacturing equipment. The earnings paths differ, however. Substrate utilization and equipment order conversion run on different schedules. We would look for customer spending to become identifiable orders and deliveries before extrapolating synchronized profit growth.
Battery exposure supplied a third pocket of strength. EcoPro rose 6.74%, EcoPro BM 5.58% and Samsung SDI 5.07%. We see that as evidence of wider risk appetite. A stronger business recovery thesis would require improving shipments, customer inventories and utilization. A one-day share-price rebound is insufficient evidence that end-market demand and profitability have already recovered.
The rally also had boundaries. Samsung Biologics fell 5.37%, while Alteogen finished unchanged. For portfolio construction, that divergence argues for checking the current earnings case in each group rather than carrying yesterday’s favored theme forward automatically. Our three areas to monitor are memory, semiconductor substrates and equipment, and battery materials.
We would become more willing to broaden exposure if the memory earnings outlook is credible, foreign buying persists and gains continue to spread through the supply chain. If breadth contracts after the results and only the largest stocks hold up, the case for chasing this rebound weakens. The decision rests on participation and specific demand evidence, rather than the size of today’s index gain.
Sources: KOSPI regular close · KOSDAQ regular close · KOSPI breadth and flows · KOSDAQ breadth and flows · 코스피 5600선 회복과 업종별 정규장 반응 · 반도체 정규장 종가와 실적 일정 · 달러·원 주간 종가 1323.7원
#KOSPI #KOSDAQ #Semiconductors #Batteries
This article is for informational purposes and does not recommend buying or selling any security. Investors are responsible for their own decisions and outcomes.